Insights for Used Car Buyers Who Serve in the Military
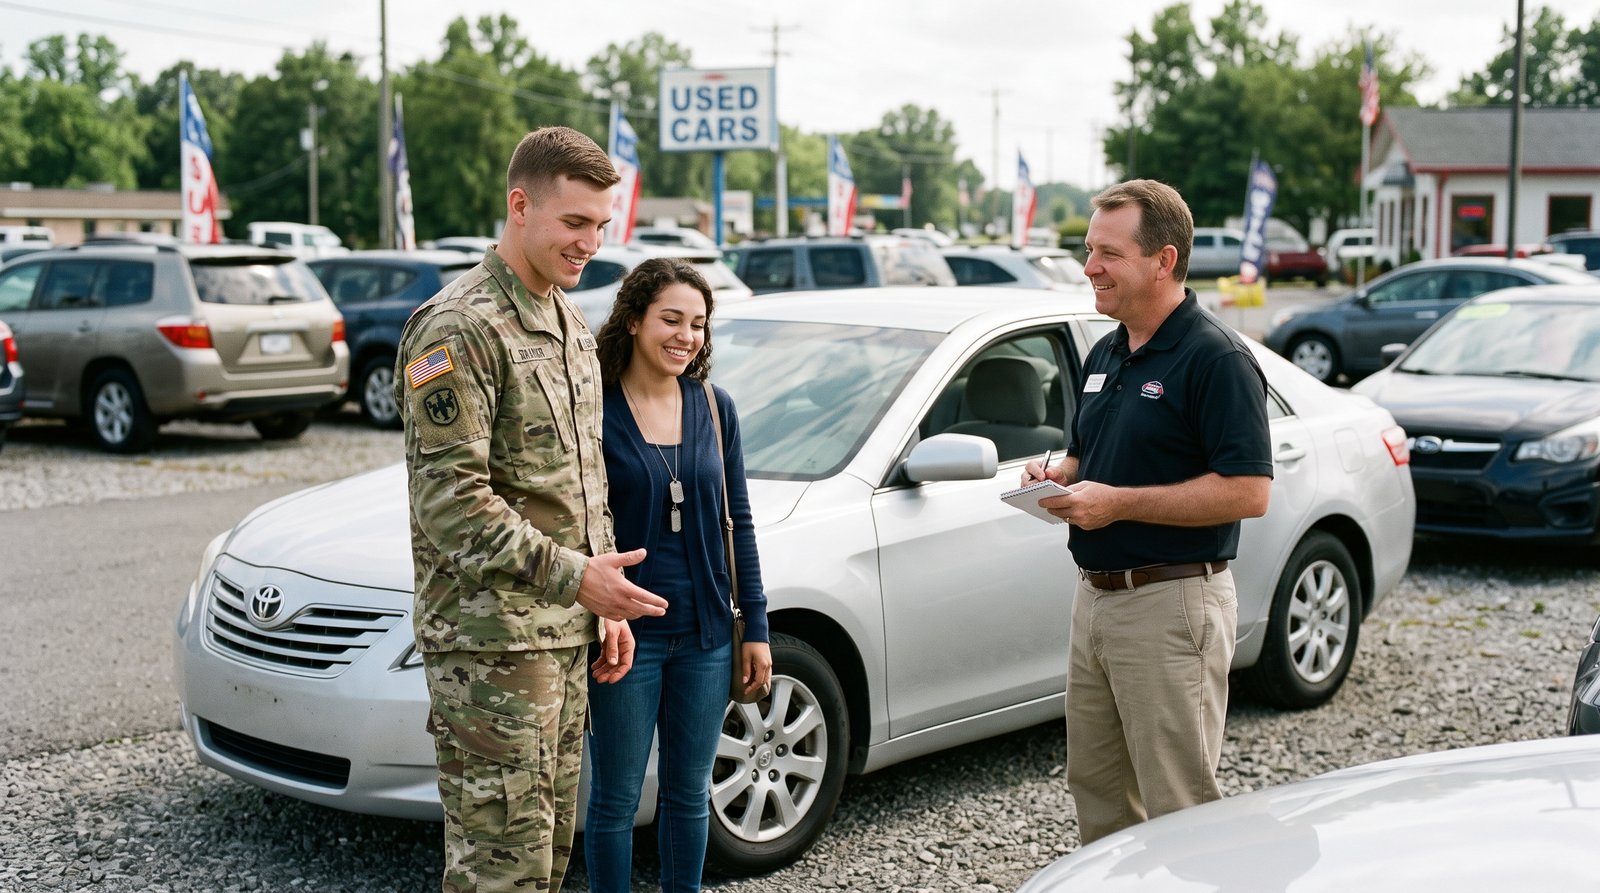
If you’re serving in the military and looking to buy a used car, you face a unique set of circumstances—and a few advantages—when it comes to vehicle purchases. Whether you’re on active duty, in the reserves, or recently separated, the process can be smoother (and smarter) when you know what to look for.
Here are some straightforward tips and insights designed specifically for military members shopping for a used car.
1. Take Advantage of Military Discounts
Many dealerships—especially those located near bases—offer exclusive military discounts on used vehicles. These can include:
- Reduced pricing
- Lower down payments
- Extended warranties
- Free maintenance packages
Tip: Always ask if a military discount is available. Be ready to show your military ID or proof of service.
2. Watch Out for Predatory Lending
Unfortunately, some lenders and dealerships target young or newly enlisted service members with bad financing deals. Be cautious of:
- High interest rates
- Long loan terms (72+ months)
- "Buy here, pay here" lots with no credit checks but aggressive terms
Know your rights under the Military Lending Act (MLA). It limits interest rates to 36% APR and prohibits certain abusive loan terms for active-duty members and their dependents.
3. Consider Your Mobility
Your duty station can (and often will) change. When buying a used car:
- Think about vehicle reliability—you don’t want breakdowns when you're PCSing across the country.
- Look for fuel efficiency if you expect to be driving long distances.
- Avoid underwater loans—owing more than the car is worth can make relocation or selling tricky.
4. Use Military-Friendly Lenders
Look into banks and credit unions that serve the military, such as:
- USAA
- Navy Federal Credit Union
- PenFed
These institutions often offer:
- Lower interest rates
- Flexible loan terms
- Auto insurance bundling
They also understand military life and can help you navigate PCS moves or deployment-related payment issues.
5. Always Check the Vehicle History
No matter how “clean” the car looks, request a vehicle history report (like Carfax or AutoCheck). Look for:
- Past accidents
- Title issues (salvage or flood)
- Consistent maintenance records
This protects your investment—and your peace of mind.
6. Get a Pre-Purchase Inspection
Whether you’re buying from a dealer or a private seller, invest in a mechanical inspection from a trusted third-party shop. It's a small cost upfront that can prevent big headaches later.
7. Know the Legal & Paperwork Process
Make sure you:
- Get the title properly transferred
- Register the vehicle in your current state of residence (not necessarily your duty station)
- Understand any state-specific tax rules (some states waive certain fees for active-duty military)
Your base legal office can often help answer vehicle-related legal questions, too.
8. Choose a Dealer Who Understands Military Life
Some dealers truly “get it” when it comes to working with military buyers—they know your needs, respect your time, and are flexible with PCS schedules or deployment concerns. If you find a dealership that offers:
- Transparent pricing
- No-pressure sales
- Flexible financing options
...you’ve found a solid partner in your car-buying journey.
Final Word: Stay Smart, Stay Protected
Serving in the military comes with unique challenges—but also with resources and protections you can use to your advantage when buying a used car.
Take your time. Ask questions. And don’t settle for less than a fair deal. Your service deserves respect, and that should include how you're treated when you buy a car.
Take this guide with you
Get a free PDF copy of this article to keep on your phone.